

In Spain, the decision between taking early retirement and continuing on the subsidy for those over 52 is more nuanced than it seems. Recent data from the BBVA Foundation and IVIE reveals a striking shift: the unemployment rate among those over 55 (9.8%) now exceeds that of the 25-54 age group (9.4%). Moreover, 45% of all unemployed individuals are over 45. For many long-term unemployed over 50, the choice boils down to either stretching the subsidy until ordinary retirement age or opting for early retirement and starting to collect a pension.
Alfonso Muñoz, a Social Security official and retirement expert, offers clear guidance in one of his videos: "It pays not to have applied for early retirement if you are receiving the subsidy for those over 52." But why? The key lies not in the subsidy amount but in the contribution to Social Security.
Find Original Home Decor sparking conversation at Grand Goldman Shop.

The Over-52 Subsidy: Modest but Valuable
The subsidy for those over 52 provides only 480 euros per month, without extra payments—equivalent to 80% of the IPREM (Public Indicator of Multiple Effects Income) and frozen since 2023. On the surface, this seems meager. However, what many overlook is that while receiving this subsidy, the beneficiary continues to contribute to Social Security.
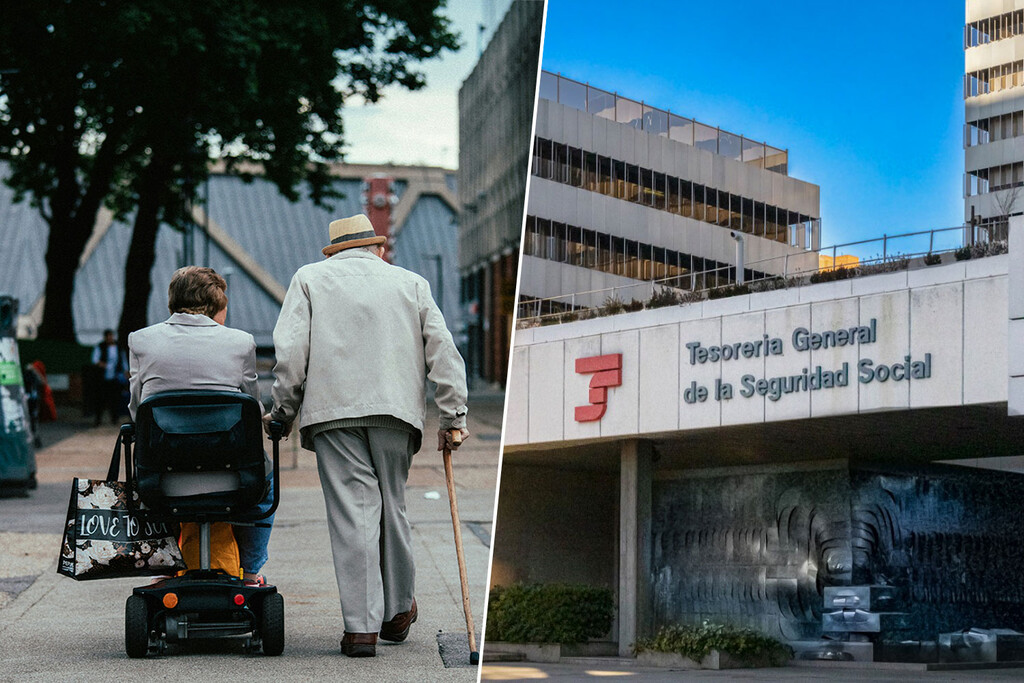
Specifically, contributions are calculated based on 125% of the minimum contribution base. This means that even though the cash benefit is low, the worker's contribution history keeps growing, which directly impacts the future pension.
How Contributions Work During the Subsidy
During the subsidy period, the Social Security administration credits contributions as if the worker were earning a salary equivalent to 125% of the minimum base. These contributions count toward the regulatory base used to calculate the retirement pension. Therefore, each month on the subsidy adds to the contribution years and increases the eventual pension amount.
In contrast, early retirement reduces the pension through reduction coefficients. The earlier you retire, the larger the cut. For example, retiring two years early can result in a 21% reduction (with 15 years of contributions) or 15% (with 40 years). These cuts are permanent and apply for life.
Early Retirement vs. Subsidy: A Financial Comparison
To understand which option is more beneficial, consider the following comparison based on typical scenarios. The table below summarizes key differences:
| Aspect | Over-52 Subsidy | Early Retirement |
|---|---|---|
| Monthly Income | 480 € (no extra payments) | Pension amount minus reduction coefficient |
| Social Security Contributions | Yes, based on 125% of minimum base | No further contributions (unless working) |
| Impact on Future Pension | Increases pension through continued contributions | Reduces pension through early retirement penalties |
| Duration | Until ordinary retirement age | Lifelong pension (with reductions) |
| Eligibility | Must meet subsidy requirements | Must meet early retirement requirements |
As the table shows, while the subsidy provides less monthly cash, it preserves and even enhances the future pension. Early retirement, although offering immediate pension access, locks in permanent reductions.
Why Experts Recommend Staying on the Subsidy
Alfonso Muñoz emphasizes that the subsidy is not just a bridge to retirement but a strategic tool. By continuing to contribute, workers can reach ordinary retirement age with a higher pension base and more contribution years. This often outweighs the temptation of early retirement, especially for those with long contribution histories.
Furthermore, the subsidy is compatible with part-time work, allowing recipients to supplement their income while still contributing. This flexibility can further improve the eventual pension.
- Continued contributions during the subsidy increase your future pension.
- Early retirement penalties are permanent and can reduce your pension by up to 21% or more.
- The subsidy amount (480 €) is modest but comes with valuable Social Security contributions.
- Part-time work is allowed while on the subsidy, boosting income and contributions.
- Long-term unemployed over 50 often benefit more from waiting until ordinary retirement age.
Who Qualifies for the Over-52 Subsidy?
To be eligible for the over-52 subsidy, applicants must be registered as job seekers, have exhausted unemployment benefits, and have contributed at least six years to Social Security (including three years for unemployment). They must also lack the required contributions for early retirement. The subsidy is granted until the recipient reaches ordinary retirement age.
For those who qualify, the decision between early retirement and the subsidy hinges on personal circumstances, but the financial math often favors the subsidy. The background to this story is set out in New Rule Cuts Early Retirement Pensions by Up to 400 Euros Monthly. A related thread runs through Spain Pension Fraud: Man Ordered to Repay €9,240 After Colombia Trips. Earlier coverage in Coast FI: The Math Formula Helping Gen Z Retire Early shows how the argument developed.
What to Watch Next
As Spain's demographic landscape shifts, policies around retirement and subsidies may evolve. The BBVA and IVIE study underscores the growing challenge of older unemployment. Workers approaching retirement should stay informed about changes to contribution rules and pension calculations. A closer look at the same subject appears in France's Retirement Timebomb: Why Crisis Will Continue. Anyone following the wider picture can start with Superannuation Early Access: Should You Tap Your Retirement Savings. The same theme surfaces in Neighbor Annoyed After Woman Takes In His Stray Cat Which Seems Neglected For A Long Time, which takes a different angle.
Consulting a Social Security expert like Alfonso Muñoz can provide personalized guidance. His advice is clear: if you're on the over-52 subsidy, think twice before applying for early retirement. The long-term benefits of continued contributions often outweigh the short-term gain. Context on how this played out before sits in Private Pensions: A Publicly Subsidised Gift to the Wealthy. A companion piece, Over-50s Unemployment Crisis Demands Jobs for Older Workers, approaches the same subject from another angle.
FAQ
What is the over-52 subsidy in Spain?The over-52 subsidy is a monthly benefit of 480 euros for unemployed individuals over 52 who have exhausted their unemployment benefits. It includes Social Security contributions based on 125% of the minimum contribution base.
The over-52 subsidy is a monthly benefit of 480 euros for unemployed individuals over 52 who have exhausted their unemployment benefits. It includes Social Security contributions based on 125% of the minimum contribution base.
How does early retirement affect my pension?Early retirement reduces your pension through reduction coefficients that depend on your contribution years and how early you retire. For example, retiring two years early can cut your pension by 15-21% permanently.
Early retirement reduces your pension through reduction coefficients that depend on your contribution years and how early you retire. For example, retiring two years early can cut your pension by 15-21% permanently.
Can I work while receiving the over-52 subsidy?Yes, part-time work is allowed while receiving the subsidy, as long as it doesn't exceed certain income limits. This can supplement your income and increase your contributions.
Yes, part-time work is allowed while receiving the subsidy, as long as it doesn't exceed certain income limits. This can supplement your income and increase your contributions.
Why do experts recommend not taking early retirement if on the subsidy?Because the subsidy includes Social Security contributions that increase your future pension, while early retirement imposes permanent reductions. Over time, the higher pension from waiting often outweighs the early pension.
Because the subsidy includes Social Security contributions that increase your future pension, while early retirement imposes permanent reductions. Over time, the higher pension from waiting often outweighs the early pension.
Browse the Shop
 Acacia frida deluxe solid wood bed frame |
Bedroom bench |
Bed chest drawers |
Lingerie dresser |
Frame base |
Mirror with jewelry storage |
30 Bathroom Vanity |
Memory foam queen mattress |
Mattresses for back pain |
Nightstand set of 2 |
Grand Goldman Shop |
Civil Lawyer
Deutschland Trikot WM 2026







