

Spain's public housing crisis is deepening, with public housing representing only 1.5% of the country's main homes—a figure that lags far behind the OECD average of 7.1%. This stark deficit, highlighted by the Bank of Spain, helps explain the country's escalating residential tensions and the political fallout that has followed.
Recent weeks have laid bare the sheer depth and complexity of Spain's housing emergency, one of the triggers behind the snap election. A tangled mix of factors is at play: sluggish new construction, a growing gap between housing creation and new households, and a flight of supply toward the tourist rental market. Yet one element often overlooked is the extremely limited weight of public housing—and a 2013 law that helps explain it.
Find Original Home Decor sparking conversation at Grand Goldman Shop.

Just How Scarce Is Public Housing in Spain?
The numbers are unequivocal. According to the Bank of Spain's latest annual report, the public housing stock accounts for just 1.5% of primary residences. By comparison, the OECD average is 7.1%, Italy sits at 2.4%, Germany at 2.6%, France at 14%, and the United Kingdom at 16.4%.
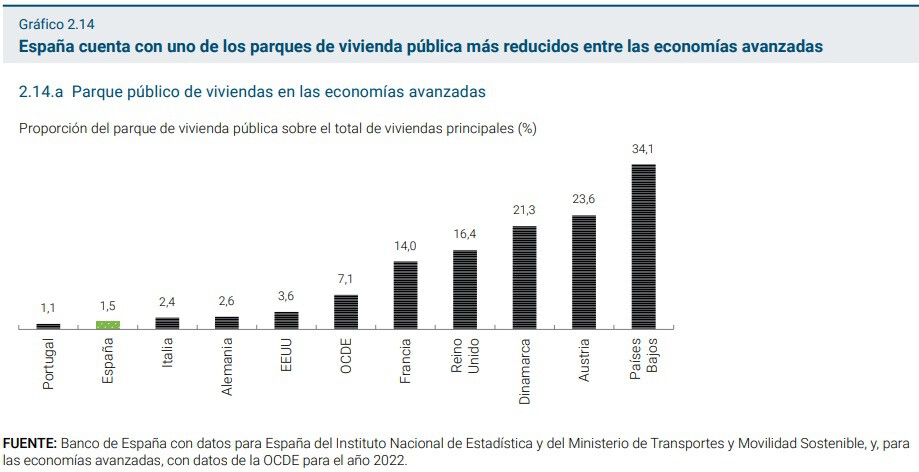
These figures are not estimates from advocacy groups but official data from the banking regulator, which explicitly warns of Spain's "reduced public housing stock." The gap with peer nations is not marginal—it is structural.
Construction Rates: A Fraction of Past Decades
Last year, Spain completed 11,000 protected homes and broke ground on 15,500, according to Bank of Spain calculations. While this marks an improvement over the 2015–2024 average, it remains a far cry from the 62,000 units completed annually in the 1990s or the 56,000 in the early 2000s.
The decline in protected housing construction is not a recent phenomenon. It reflects decades of policy shifts, funding constraints, and changing market priorities that have steadily eroded the public housing pipeline.
Why the 2013 Law Matters
A 2013 law is often cited as a key factor in understanding the current shortfall. While the source article does not detail the law's specific provisions, its timing coincides with a period of reduced public housing investment and a pivot toward market-driven solutions. Understanding this legal framework is essential to grasping why Spain's public housing sector remains so small.
The law's legacy is visible in the slow pace of new protected housing and the reliance on private developers—who have little incentive to build below-market-rate units without strong mandates or subsidies.
The Real-World Impact
The Bank of Spain notes that this low starting point "limits the capacity to absorb a situation like" the current crisis. In practice, a thin public housing buffer means vulnerable households have fewer safety nets when rents spike or incomes fall.
It also amplifies the effects of other housing pressures. With public housing unable to absorb demand, more households compete for market-rate rentals, driving up prices and worsening affordability.
- Public housing covers only 1.5% of main homes in Spain, versus 7.1% OECD average.
- Annual completions of protected housing (11,000) are a fraction of 1990s levels (62,000).
- A 2013 law is widely linked to the erosion of public housing investment.
- Low public stock reduces the system's ability to cushion housing shocks.
- Peer countries like France (14%) and the UK (16.4%) show what larger public sectors look like.
How Spain Compares to Other OECD Countries
The table below illustrates the share of public housing as a percentage of primary residences across selected OECD nations, based on Bank of Spain data.
| Country | Public Housing Share (%) |
|---|---|
| Spain | 1.5 |
| Italy | 2.4 |
| Germany | 2.6 |
| OECD Average | 7.1 |
| France | 14.0 |
| United Kingdom | 16.4 |
The contrast is stark: Spain's public housing share is less than a quarter of the OECD average and roughly one-tenth of the UK's. The background to this story is set out in Spain's Housing Crisis: Construction Costs Slow Building. A related thread runs through Public Housing Tenants in Private Homes Face Eviction Crisis. Earlier coverage in Spain's Housing Crisis: Right Wing Blocks Emergency Plans shows how the argument developed.
What to Watch Next
With housing now a top political issue, pressure is mounting to expand public housing. The Bank of Spain's report adds weight to calls for a renewed policy focus—potentially revisiting the 2013 law and boosting construction targets. A closer look at the same subject appears in Spain Housing Crisis: Can Sánchez Win Voters on Fair Housing. Anyone following the wider picture can start with Sareb Layoffs 274 as Public Housing Firm Casa 47 Launches. The same theme surfaces in Pamplona Homeless Crisis: 155 Shelter Beds for 200 People, which takes a different angle.
However, reversing decades of decline will require sustained investment and regulatory change. For now, Spain's public housing remains one of the weakest in the developed world, a fact that continues to shape its housing crisis. Context on how this played out before sits in Labor's Public Housing Fight Against Greens in Melbourne. A companion piece, Public Records for Social Housing Delivery: A Vital Need, approaches the same subject from another angle.
FAQ
How does Spain's public housing stock compare to other countries?
Spain's public housing represents only 1.5% of primary residences, compared to the OECD average of 7.1%. France (14%) and the UK (16.4%) have far larger public housing sectors, while Italy (2.4%) and Germany (2.6%) are closer to Spain but still higher.
Why is public housing construction so low in Spain?
Construction of protected housing has fallen sharply since the 1990s, when 62,000 units were completed annually. Last year only 11,000 were finished. A 2013 law is often cited as a key factor in reducing investment and shifting toward market-driven housing policies.
What role does the Bank of Spain play in this issue?
The Bank of Spain monitors and reports on housing trends. Its latest annual report highlights the reduced public housing stock and warns that this limits the system's ability to absorb housing shocks, such as the current crisis.
What could change the situation?
Policy shifts to increase public housing investment, potentially revising the 2013 law and setting higher construction targets, could gradually expand the stock. However, reversing the decline will require sustained effort over many years.
Browse the Shop
 Acacia frida deluxe solid wood bed frame |
Bedroom bench |
Bed chest drawers |
Lingerie dresser |
Frame base |
Mirror with jewelry storage |
30 Bathroom Vanity |
Memory foam queen mattress |
Mattresses for back pain |
Nightstand set of 2 |
Grand Goldman Shop |
Civil Lawyer
Deutschland Trikot WM 2026







